 Saturday, September 26, 2026
 Modern education equips students with strong academic knowledge, yet many essential life skills remain underemphasized. As curriculum relevance evolves, integrating practical financial literacy, communication, critical thinking, and emotional intelligence can better prepare students for real-world success beyond the classroom.

The modern educational landscape is undergoing a massive structural debate regarding curriculum relevance. While modern high schools successfully guide students through advanced academic fields—such as calculus equations, organic chemistry pathways, and historical timelines—they frequently graduate young adults who are completely unequipped to navigate the complex financial realities of the real world.
Entering adult life without a baseline understanding of money management creates severe personal and economic risks. Today's youth step into a highly digital financial ecosystem filled with easy consumer credit lines, deceptive "Buy Now, Pay Later" (BNPL) applications, and predatory student loan pipelines.
Failing to establish early financial literacy leaves young adults highly vulnerable to severe monetary mistakes. Millions of students pick up high-interest credit card debt, mismanage their initial salaries, or fall victim to opaque online speculative assets, locking themselves into a cycle of financial stress before they even enter the workforce.
Transitioning from an abstract academic focus to a practical, school-based financial literacy framework solves this operational gap. By embedding money management principles directly into early education, we can transform personal finance from a source of adult anxiety into a powerful tool for lifelong security, wealth building, and institutional confidence.
1. The Behavioral Economics of Early Financial Training
To build a school program that actually changes future behavior, we must understand the psychology behind financial habits. Financial literacy is not just a collection of mathematical facts; it is a set of daily behavioral patterns.
Studies in behavioral economics show that core money behaviors—including impulse control, delayed gratification, and basic saving habits—are largely formed in childhood by the age of seven.
When personal finance training is missing during formative years, individuals naturally pick up unstructured, often unhealthy habits from advertising or peer circles. Waiting until a student turns eighteen and signs their first loan contract to explain credit scores is a structural mistake.
Early financial education uses the brain's natural flexibility during youth to turn compound interest calculations, regular saving routines, and careful budgeting habits into automatic default choices.
2. Core Infrastructure: The Modern Money Literacy Framework
To successfully prepare students for adult life without adding unnecessary strain to existing school schedules, a practical financial curriculum should focus on four evidence-based operational pillars.
Pillar A: Demystifying Credit Architecture and Debt TrapsMany young adults view credit cards as extra available cash rather than high-interest loans that must be paid back promptly. A modern classroom framework must explain the underlying mechanics of credit tracking systems:
- Credit Score Mechanics: Teach students exactly how a credit score is calculated, showing how missing a single payment can damage their score and make future needs—like renting an apartment or securing a car loan—much more expensive.
- The High Cost of Minimum Payments: Walk students through real credit card statements, using simple math to show how making only the bare minimum payment on a balance can trap a consumer in high-interest debt for decades.
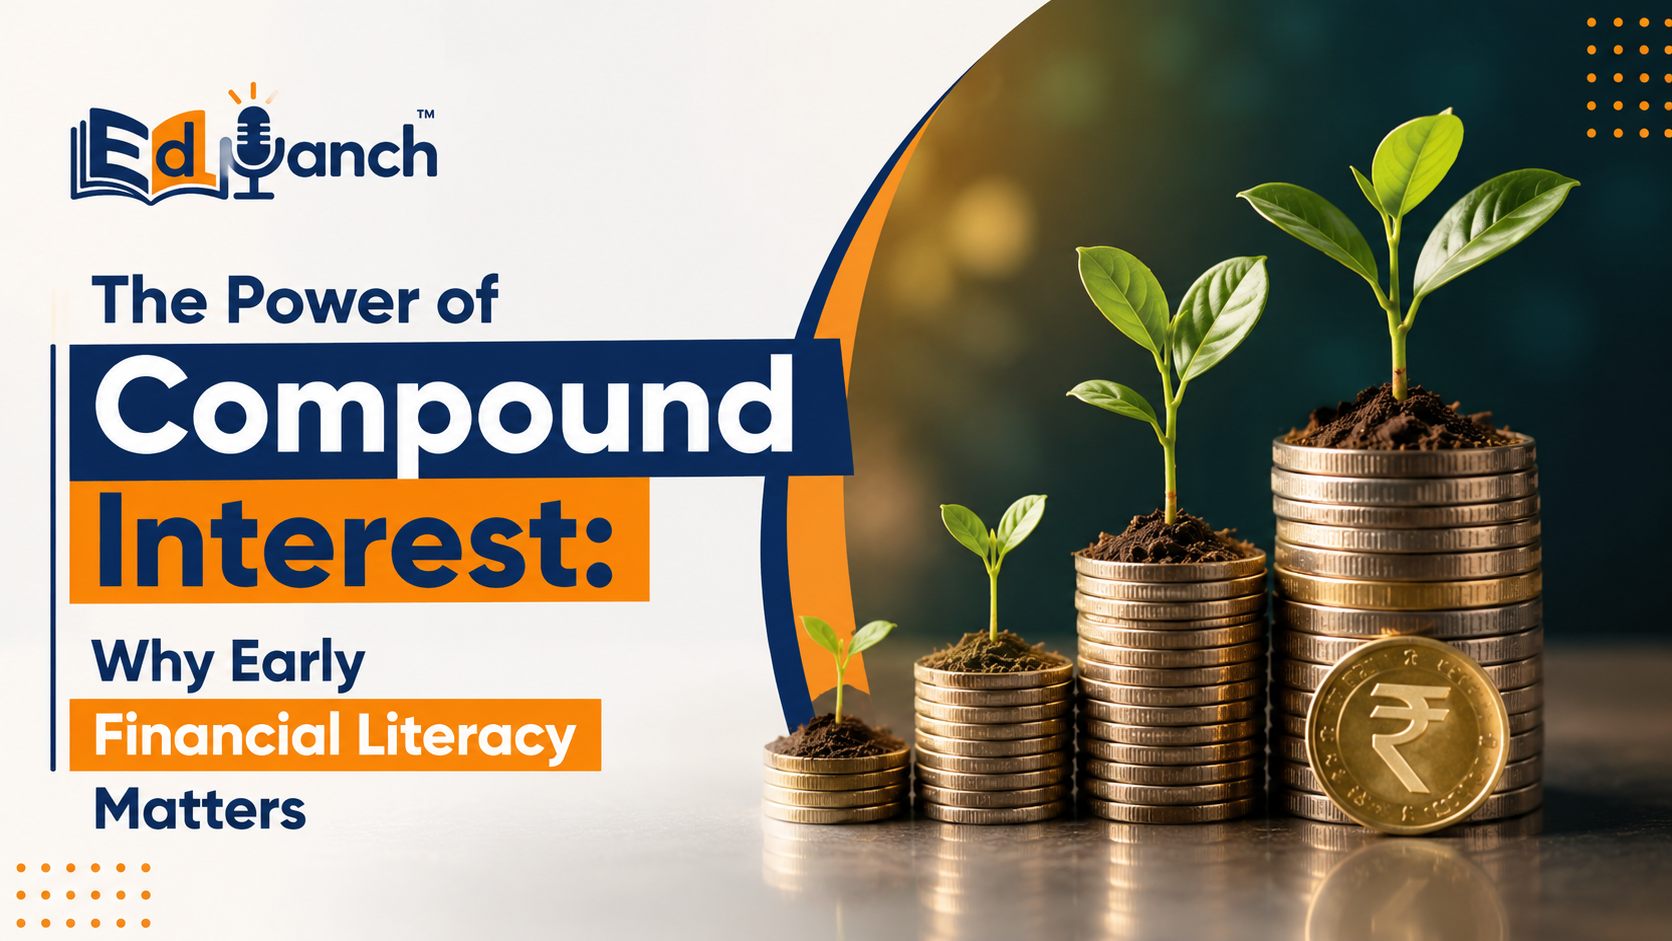
Compound interest is a powerful financial tool that works best the earlier you start. Students need to see the clear mathematical difference between simple interest and compound growth, illustrating how small, regular investments made during their teenage years can grow significantly over time.
The primary advantage of early saving is time. When an individual starts allocating small amounts at an early age, like 16, it minimizes the daily financial strain required to build wealth.
As the returns on those initial deposits are earned, the interest automatically rolls back into the principal balance, generating entirely new layers of growth. This continuous re-investment builds massive momentum over a multi-decade horizon.
Eventually, the accumulation transitions into a phase of exponential escalation, where the interest earned far outpaces any late-stage cash additions, providing permanent lifetime financial security.
Pillar C: Budgeting and Navigating the Digital EconomyIn a world dominated by digital wallets, tap-to-pay apps, and online shopping, money has become invisible. When completing a purchase requires only a biometric scan or a single click, the psychological pain of spending money disappears, making impulse buying far too easy.
Schools must teach students how to manage digital cash using practical budgets like the 50/30/20 rule—allocating 50% to essential needs, 30% to personal wants, and routing the remaining 20% straight into a dedicated savings or investment account—ensuring they maintain control over their money in a cashless society.
Pillar D: Evaluating Student Loans and Educational ROIsHigher education is one of the largest financial investments a person will ever make, yet we routinely ask seventeen-year-olds to sign for massive loans without any understanding of future repayment terms.
A high-performance financial literacy program teaches students how to calculate the true return on investment (ROI) of a college degree, compare starting field salaries against projected monthly loan payments, and explore more affordable paths like community college routes or public university options.
Comparative Matrix: Fragmented Academic Math vs. Integrated Financial Literacy
The table below contrasts the limits of standard abstract mathematics with the real-world performance advantages of an integrated financial literacy program.
|
Educational Competency Pillar |
Standard Abstract Academic Math |
Integrated Practical Financial Literacy |
The Real-World Strategic Advantage |
|---|---|---|---|
|
Interest Rate Education |
Calculating theoretical interest on abstract textbook problems. |
Analyzing real credit card terms and compound wealth tools. |
Literacy: Teaches students how to leverage compounding early while avoiding high-interest debt traps. |
|
Banking and System Fluidity |
Zero practical application; focus remains entirely on formulas. |
Navigating digital bank portals, checking accounts, and hidden fees. |
Literacy: Builds confidence in using daily financial tools safely. |
|
Debt Evaluation Strategy |
Solving abstract equations with zero personal context. |
Calculating true student loan ROI and monthly repayment terms. |
Literacy: Prevents young adults from taking on unmanageable college debt. |
|
Tax and Income Comprehension |
Flat percentage problems with no real-world link. |
Reading a standard paystub and tracking income tax brackets. |
Literacy: Prepares graduates to understand their actual take-home pay and tax duties. |
|
Behavioral Habits Focus |
Purely analytical; ignores individual choices. |
Enforcing budgeting systems like the 50/30/20 rule. |
Literacy: Develops strong habits of delayed gratification and consistent saving. |
3. High-Performance Action Plan for Educators and Policy Makers
To successfully upgrade your school network's curriculum and launch practical financial literacy classes across your classrooms, execute this multi-phase operational protocol:
- Execute a Complete Core Curriculum Gap and Re-Calibration Audit
Phase 1
Identify scheduling spaces early. Review current math and social studies guidelines to locate open blocks where practical finance modules can be integrated without overloading the primary calendar. - Deploy Specialized Interactive Simulation and Budgeting Tools
Phase 2
Provide engaging learning tools. Introduce digital trading sandboxes, mock budgeting applications, and real-world loan simulators, allowing students to navigate financial scenarios safely without real-world risk. - Launch Ongoing Teacher Training and Standardized Testing Sweeps
Phase 3
Maintain high educational quality. Run regular workshops to equip educators with up-to-date financial tools, and track student progress using standardized metrics to ensure long-term program success.
Actionable Strategy: Your Long-Term Governance Roadmap
- Link Student Learning Portals Natively with the Universal APAAR ID Grid: Ensure all financial literacy completions, upskilling badges, and economic certifications sync cleanly with national student networks. Storing achievements natively under a student's unique APAAR ID via the digital Academic Bank of Credits (ABC) repository preserves their verified learning journey, simplifies tracking, and builds a strong portfolio for future opportunities.
- Build Strategic Partnerships with Local Verified Banking Networks: Connect classroom lessons with real-world practice. Partner with verified public financial institutions to offer students safe, fee-free student checking accounts, allowing them to practice budgeting and saving using actual digital banking tools under parental supervision.
- Conduct Semi-Annual Regional Student Financial Capability Reviews: Keep an objective eye on educational performance. Appoint a curriculum evaluation officer to monitor student progress twice a year, tracking how well graduates understand budgeting, debt rules, and basic investing, and adjusting lesson plans to fix any emerging gaps before graduation.
Frequently Asked Questions (FAQs)
Q1. Why is financial literacy rarely taught in standard secondary school systems?Traditional curricula prioritize abstract testing paths designed for college admissions, often leaving practical life skills out of the primary schedule due to time constraints and a lack of standardized personal finance teacher training.
Q2. How early should children begin learning basic money management concepts?Basic financial habit patterns begin taking root by the age of seven. Introducing simple concepts like delayed gratification, separating needs from wants, and using physical coin jars early builds strong foundations before digital spending begins.
Q3. What is the 50/30/20 budgeting rule, and how does it help teenagers?It is a simple, highly effective budgeting system: allocate 50% of your income to essential needs, 30% to personal wants, and route the remaining 20% straight into a dedicated savings or investment account, building automatic saving habits.
Q4. How does compound interest differ from simple interest over a long timeline?Simple interest pays returns only on the original amount saved. Compound interest pays returns on your original savings plus all the accumulated interest rolled back in, triggering an exponential growth curve that builds significant wealth over time.
Q5. What is the role of an APAAR ID in modern student skill tracking?An Automated Permanent Academic Account Registry (APAAR) ID serves as a secure, lifelong digital identity that records a student's verified academic credits, technical certifications, and practical upskilling awards cleanly across distinct platforms.
Q6. Why do digital wallets and tap-to-pay apps increase a student's impulse spending?Physical cash creates a direct psychological alert when handed over. Digital apps make money invisible; completing a purchase requires only a biometric scan, removing the friction of spending and leading to unmonitored impulse buying.
Q7. How can a student accurately calculate the true economic ROI of a college degree?Students should research average entry-level salaries for their target field, compare those projections against the total cost of tuition and loan interest, and ensure their estimated monthly loan payments do not exceed 10% of their net take-home pay.
Q8. What parameters are actively monitored on a 360-degree student financial capability scorecard?A holistic scorecard tracks data beyond basic test scores, cross-referencing credit calculation skills, budgeting app accuracy metrics, real-world loan interest analysis speeds, income tax filing awareness, and basic investment risk choices.
Q9. How fast can a school expect to see an improvement in student financial habits after launching a program?When an educational network updates its strategy to deploy interactive budgeting software, run mock loan simulations, and integrate practical finance modules, the improvement is steady. You can observe improved financial decision-making within 4 to 6 weeks of active execution.
Q10. What immediate steps should a school board take if local graduates display high debt vulnerability metrics?The board must act swiftly: immediately deploy short, targeted personal finance bootcamps for senior classes, integrate automated loan simulation tools into the mandatory graduation path, establish free family financial counseling clinics, and update the primary curriculum to secure early money management classes for upcoming terms.